Model implementation
From mathematical specification to production code, with the tests and documentation to keep it maintainable.
Model & system development
We build the bridge between regulatory methodology and the numbers that risk, finance and the regulator actually see. We include the tests and documentation that keep it working.
Where we help
A model is not delivered until it runs reliably, can be explained, and can be changed without breaking something else.
From mathematical specification to production code, with the tests and documentation to keep it maintainable.
Data flows, compute, storage and integration for counterparty credit risk and market risk systems.
Model documentation, change control, validation evidence and the operating model around the system.
Synthetic portfolios, regression tests, back-testing pipelines and automated quality reporting.
Gap analysis across collection, transformation and storage, with practical remediation plans.
Building and leading mixed teams of quants, engineers and business analysts to deliver the system.
Selected platform
Virtufin mirrors every trade, stream and exchange into a live, event-driven simulation, so strategies can be tested against production data without production risk.
Patrick Häner manages a team of AI agents delivering the platform.
Visit virtufin.com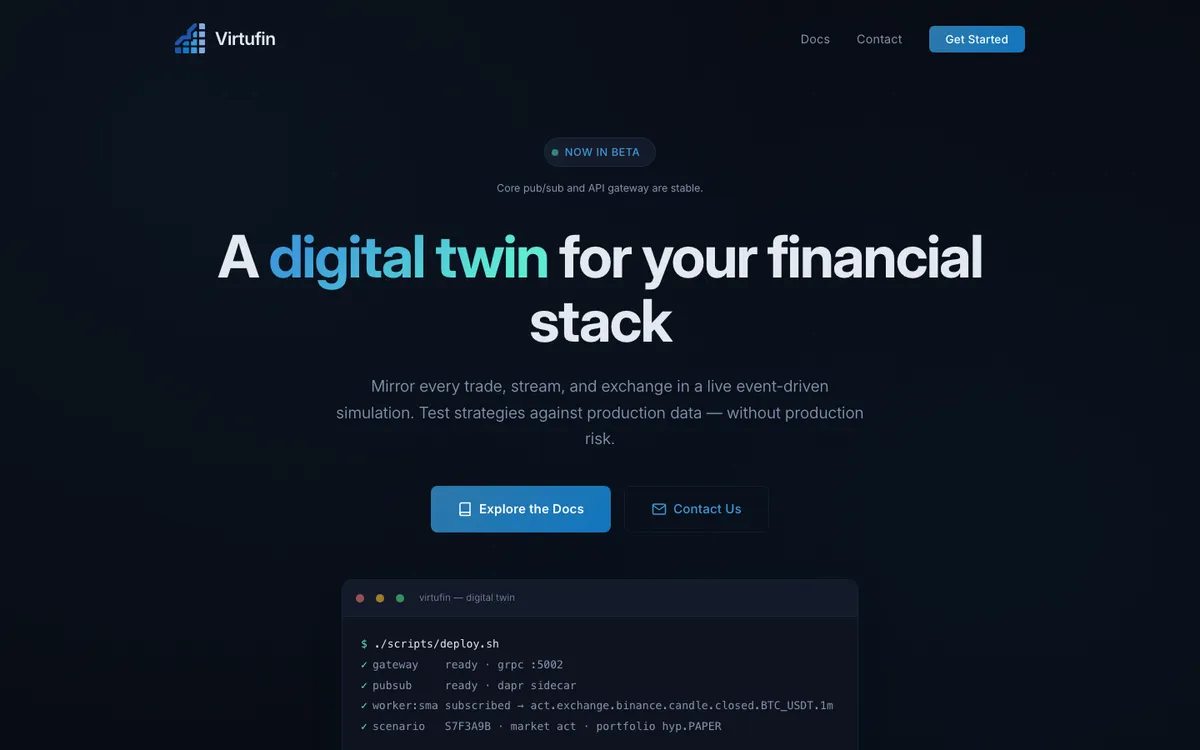
Engagement
We work from the mathematical definition through to the production system, the tests and the documentation the institution needs to operate it.
Selected work
The delivery patterns are representative; clients are not named.
Global Japanese bank
An IMM-compliant counterparty credit risk system built from scratch by a team of quants, engineers and analysts.
The bank planned to apply for an IMM waiver under Basel II to reduce regulatory capital, but did not have an IMM-compliant counterparty credit risk system.
As global head of counterparty credit risk analytics, Patrick Häner built and led a team of quants, software engineers and business analysts to deliver the system from scratch.
The cost of building the system was a fraction of the regulatory capital it helped to save.
Global South African bank
A synthetic-portfolio, exposure and reporting pipeline that made IMM back-testing repeatable.
The bank used a third-party credit exposure system and needed to build IMM-compliant back-testing capability around it.
Using C#, IronPython and R, we built a system that created synthetic portfolios, calculated exposures and produced automated back-testing reports.
The client met the back-testing requirements under IMM with a process that could be repeated and audited.
FAQ
Most questions can be answered quickly. If yours is not here, ask directly.
Both. We work from methodology and prototype through production implementation, testing, documentation and handover.
Yes, including third-party and in-house risk systems, data platforms and reporting infrastructure.
We map collection, transformation and storage, identify gaps and agree a practical remediation plan with your team.
Yes, including model documentation, test evidence, controls and runbooks so the system can be operated and changed.
Replacing a legacy system or adding a new model? We can help with the architecture, the implementation and the evidence.